Each row begins with the prior row's closing principal. Interest equals opening principal times the periodic rate. Principal reduction equals the total payment minus interest. Closing principal equals opening principal minus that reduction.
interest_t = opening balance_t × i
principal_t = payment - interest_t
closing balance_t = opening balance_t - principal_t
At a positive fixed rate with a level payment, interest generally declines and principal reduction generally rises. The first payment is not “mostly interest” by definition; the actual proportions depend on rate and term. In the Cedar Works 48-month example, a 0.5% monthly rate on $48,000 opening principal and a $1,127.281394… level payment produce $240 interest and $887.281394… principal in the first row.
The analytical schedule in this module uses full precision and should end within numerical tolerance of zero. Real servicers often round currency each period and adjust a final payment. Contract terms, fees, day counts, late payments, prepayments, variable rates, and disclosure rules can produce a different schedule. A classroom reconciliation is not a loan quote.
Accounting learners can use the schedule to understand principal-versus- interest evidence, but actual recognition, effective-interest accounting, classification, and disclosure require applicable guidance. Finance learners can use it to inspect cash-flow timing and total interest, but those amounts do not alone establish affordability or product suitability.
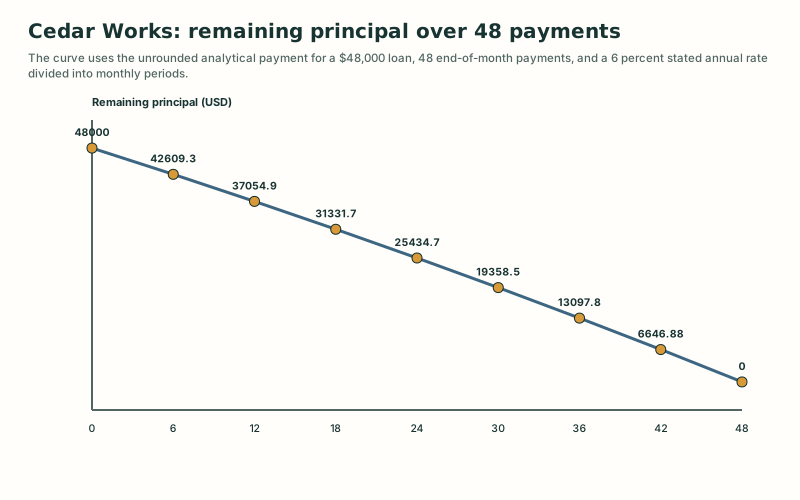
Cedar Works loan balance over 48 payments
Detailed visual description
The generator calculates the monthly periodic rate, unrounded level payment, and remaining analytical balance, then plots the opening balance and every sixth payment through payment 48.
Put the concept to work
Understand this concept
- Explain how periodic interest, payment, principal reduction, and closing balance connect in each row of a level-payment amortization schedule.
Analyze this concept
- Build and reconcile an analytical level-payment schedule, verify total principal and ending balance, and diagnose rate, timing, sign, or rounding mismatches.
Learning resources
Choose a lesson, try an application, or inspect the sources behind this concept.
Build on these ideas
- Level payment — Apply
To analyze this concept: Required. Each schedule row uses the computed level payment.
- Level payment — Understand
To understand this concept: Required. The schedule allocates a previously defined total payment.
- Periodic interest rate — Apply
To analyze this concept: Required. Interest must use the rate matching each payment interval.
Lessons
Worked examples and cases
Practice
Common mistaken ideas
Sources
Broader topics
Related concepts
Show 2 more related concepts
Use this idea next
- Installment note — Apply
Required level here: analyze. Required. The payment schedule allocates each cash amount between interest and principal.