Detailed visual description
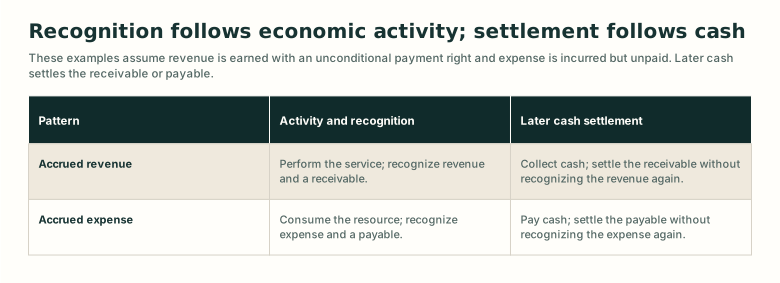
For accrued revenue, performing the service creates revenue and a receivable; later collection settles the receivable. For accrued expense, consuming the resource creates expense and a payable; later payment settles the payable. Neither later cash event repeats the earlier revenue or expense recognition.
Review apparatus
Visual provenance and review
- Technique
- ai specified svg
- Role
- explanatory
- Review state
- revised
- Model source
- google · google:gemini-2.5-pro
- Rights
- CC0-1.0 · Project-authored deterministic rendering of a reviewed model-assisted specification
Review notes
- The real Google call correctly centered the separation between the economic-activity period and the cash period.
- The raw proposal encoded unsupported timeline lanes as JSON strings and omitted required renderer fields, so it failed the deterministic renderer gate.
- The accepted comparison-table specification preserves the two proposed accrual patterns without retaining the proposal's unnecessary example amounts.
Retained model-call description
scripts/figures/llm_spec.py constrained proposal using the complete C:accrual-basis-accounting record; the retained response contains the learning question, rationale, proposed specification, and fact-check list.