Detailed visual description
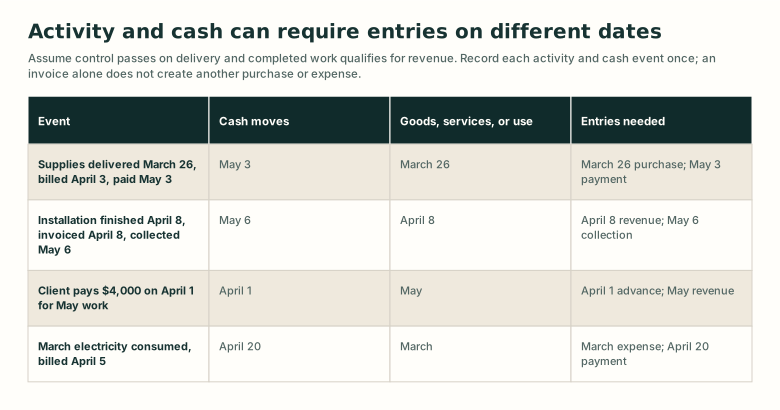
Four standalone timing examples assume qualifying recognition and control on delivery. Supplies received March 26 are recorded then; payment May 3 settles the payable. Installation completed and billed April 8 creates revenue and a receivable; May 6 collection settles it. A $4,000 April 1 advance creates a liability; May work earns the revenue. March electricity creates expense and a payable; April 20 payment settles it. Every row includes separate accounting for the activity and cash event.
Review apparatus
Visual provenance and review
- Technique
- deterministic svg
- Role
- explanatory
- Review state
- candidate
- Rights
- CC0-1.0 · Project-authored teaching diagram
Review notes
- Dates are internally consistent with the invoice figure and with the lesson prose.