On this page
A contra account preserves two facts that a single net balance would collapse: the gross recorded amount and the cumulative offset. The pair supports both a net presentation and a traceable rollforward.
Opposite normal sides
An asset is ordinarily debit-normal, so a contra-asset is ordinarily credit- normal. If Equipment has a $36,000 debit balance and Accumulated Depreciation has a $6,000 credit balance, their linked presentation is:
Equipment, gross cost                  $36,000
Less: Accumulated Depreciation          (6,000)
Carrying amount                        $30,000
The $6,000 credit does not turn Equipment into a liability. It is a separate credit-normal account whose relationship to Equipment produces the net amount.
Contra structures can also offset liabilities, equity, revenue, or expense. Their names and uses differ, but the foundational pattern remains: classify the related account, identify the opposite normal side, and preserve the linkage.
Why not credit the asset directly?
Crediting Equipment for every depreciation entry would reduce its recorded gross amount and make it harder to distinguish original cost, additions, disposals, and cumulative allocation. A separate contra account retains both the gross-cost history and the offset history.
That separation also matters in data. An analyst must join or map the contra to the correct related asset class. Summing every debit and credit balance without that relationship can misstate gross investment, carrying amount, or expense.
Contra does not mean error
An abnormal balance is an unexpected side that requires investigation. A contra account is intentionally designed with the opposite normal side. The two can look similar in a sign-only export, so account definition and relationship—not sign alone—must drive interpretation.
Boundaries
A contra account does not by itself determine valuation, recognition, or presentation under applicable standards. Some offsets are presented net, some require separate disclosure, and some systems store them through dimensions rather than one universal account title. This concept establishes the linked gross/offset model, not every specialized allowance or reserve.
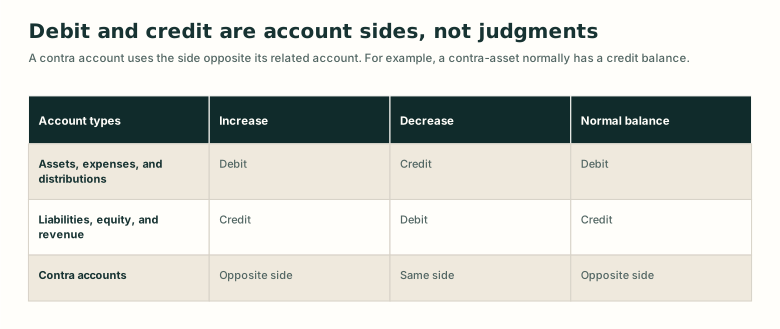
Debit and credit effects by account type
Detailed visual description
Assets, expenses, and owner distributions increase with debits, decrease with credits, and normally have debit balances. Liabilities, equity, and revenue increase with credits, decrease with debits, and normally have credit balances. A contra account increases and normally carries a balance on the side opposite its related account. It decreases on the same side that increases the related account. For example, Accumulated Depreciation is a contra-asset with a normal credit balance.
Put the concept to work
Understand this concept
- Explain how a contra account offsets a related gross balance on the opposite normal side while preserving separate account histories.
Apply this concept
- Determine the normal side and basic gross-minus-contra presentation for a linked account pair without netting their ledger histories.
Learning resources
Choose a lesson, try an application, or inspect the sources behind this concept.
Build on these ideas
- Account — Understand
To understand this concept: Required. A contra account is a separate accumulation record linked to, but not identical with, another account or class.
- Contra account — Understand
To apply this concept: Required. Application requires treating the offset as a linked account rather than a correction to the gross record.
- Normal balance — Apply
To apply this concept: Required. The learner must map the related class and its contra to opposite normal sides.
Show 1 more prerequisites
- Normal balance — Understand
To understand this concept: Required. The defining recording pattern uses the side opposite the related account's ordinary balance.
Lessons
Worked examples and cases
Practice
Common mistaken ideas
Sources
Broader topics
More specific topics
Related concepts
Use this idea next
- Accumulated depreciation — Understand
Required level here: apply. Required. Accumulated depreciation is interpreted through its linked opposite-normal-side relationship with the depreciable asset.
- Allowance for credit losses — Understand
Required level here: understand. Required. The allowance reduces presentation without replacing the gross claim.
- Contra account — Apply
Required level here: understand. Required. Application requires treating the offset as a linked account rather than a correction to the gross record.
Used in these readings
These chapters explain or apply this concept. The label states how the chapter uses it.